

Amex
by American Express
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
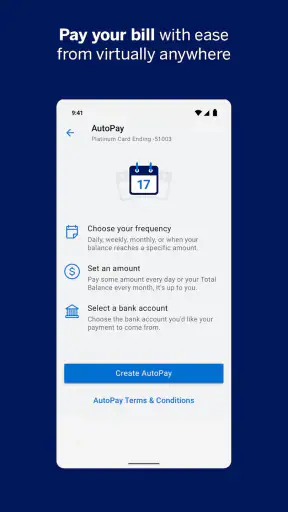
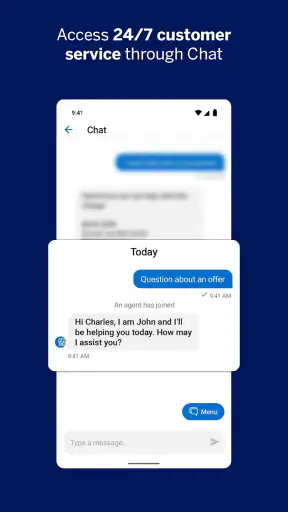
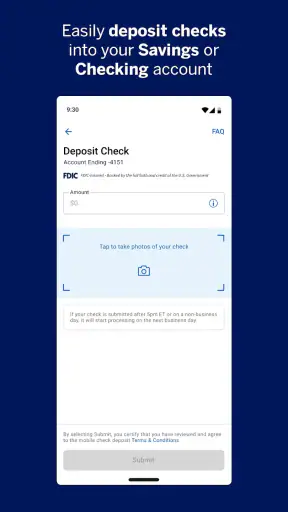
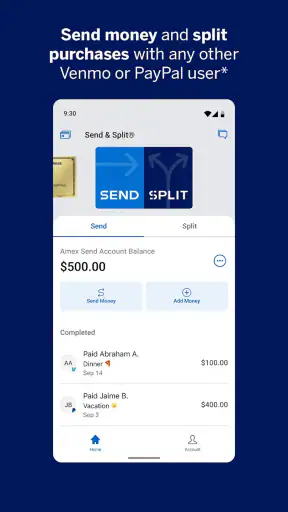
 Analysis by Getfullapps
Managing an American Express account from a phone is less about flashy extras and more about removing small obstacles from everyday money tasks. I tested the Amex mobile app as a finance tool for checking an account, making payments, and keeping rewards within reach, and I found it most useful when treated as a regular part of a card routine rather than an app opened only during a problem.
The app is free, made by American Express, and available for everyone from a content-rating perspective. Its long presence on mobile, dating back to December 2, 2010, is reflected in a mature layout that focuses on account access instead of trying to become a full budgeting platform. The current version is 7.32.2, and the app has reached over ten million installs, with a 4.8 average from around one hundred thousand ratings. Those figures suggest a well-established service, but my experience is that its value depends heavily on whether you already use American Express.
How I use Amex for the everyday account routine
My preferred starting point is simple: open the app when I need a current view of the account, check the balance and recent activity, then decide whether I need to act immediately. That sequence sounds obvious, but it prevents a common mistake with credit-card apps: making a payment without first looking for a recent purchase, pending item, or unexpected change.
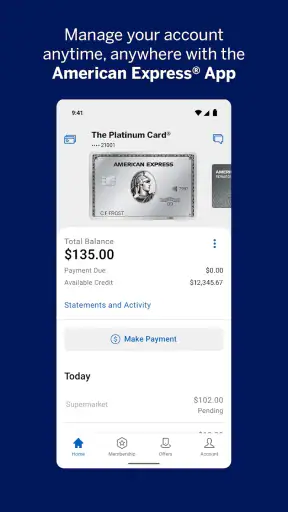
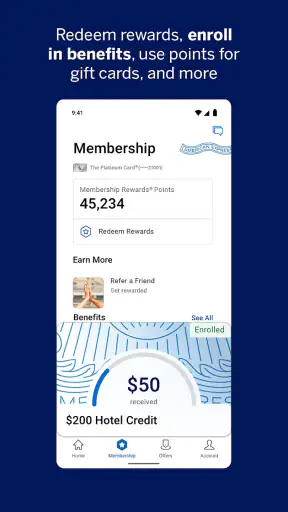
The main workflow is built around the tasks most cardholders repeat. You can access your account, review the balance, make a payment, and look at rewards. The store summary highlights secure account access, balance viewing, payments, and reward redemption, and those are the areas where the app feels most purposeful. I do not have to move through a general financial dashboard before reaching the card information that matters.
A realistic example is paying a card after receiving a salary or checking spending before a weekend away. I would first review recent transactions, identify anything still pending, and then choose a payment amount with a clearer picture of what has actually posted. That habit is more useful than simply opening the app and tapping the first payment option. It gives me a chance to notice a duplicate charge or a purchase I do not recognize before money leaves my account.
The app also works well for a quick reassurance check. If I have used the card several times during the day, I can look at the account without waiting for a desktop session. That is particularly convenient when I want to confirm whether a payment or purchase has appeared. The experience is not a replacement for careful statement review, but it makes frequent small checks practical.
Rewards are another reason to return. I like having account activity and redemption in the same mobile environment rather than switching between a card app and a separate rewards service. Still, I would not redeem points impulsively just because the option is visible. The better approach is to check the available choices when I already know what I want to do with the rewards, then compare the value and conditions shown in the app before confirming.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The strongest everyday habit is review first, action second. That applies to payments, rewards, and account security. The app makes those actions accessible, but it cannot decide whether a payment amount fits my wider finances or whether a reward redemption is worthwhile. Its convenience is best used to support a decision, not replace one.
What the app does well for existing cardholders
The biggest advantage is concentration. An American Express customer can handle several common account tasks in one place, without relying on a browser every time. The app feels aimed at people who want an account companion that is available during ordinary moments: checking a balance in a queue, reviewing a purchase after leaving a shop, or making a payment while away from a computer.
I also appreciate that the experience is specific to American Express rather than pretending to be a complete financial command center. If your main need is to operate an Amex account, a focused tool can be easier to understand than a broad money-management app that combines bank accounts, investments, budgets, and cards into one crowded screen.
That focus has a practical benefit for families and busy users. The person responsible for a card can establish a repeatable check-in routine without opening several services. I would still keep a separate personal record for larger financial planning, but the app is convenient for the operational side of card ownership.
Where the baseline workflow falls short
The app is not the right answer for someone searching for a complete household budget. Its purpose is centered on American Express account access, payments, and rewards, so users who need a unified view of accounts from several providers may prefer a dedicated budgeting or banking app. Adding another service just to see the bigger picture may be worthwhile if your finances extend well beyond one card.
It is also not a substitute for a detailed statement archive or a careful reconciliation process. For routine checks, the mobile view is efficient. For investigating a long sequence of transactions or organizing records for a larger financial review, a larger screen and a more deliberate process may be more comfortable. I see the app as the fast lane for account management, not the entire road.
Settings and account habits worth checking
I recommend spending a few minutes examining the app’s available account and security controls instead of accepting the default routine. The exact options can depend on the account and the app version, so I would not assume every American Express customer sees an identical menu. The useful principle is to look for controls that affect how you access the account, review activity, and manage payments, then choose settings that match how you actually use the card.
Security deserves particular attention because a finance app is only convenient when access remains controlled. I would use the strongest sign-in method offered on the device and avoid treating an unlocked phone as harmless. If someone else occasionally uses your phone, the distinction between a quick account check and full account access matters. A short review of sign-in behavior can prevent the app from becoming too easy to open casually.
Notifications are worth approaching selectively. Alerts can help me notice activity or remember an account task, but too many messages quickly become background noise. My preference is to keep notifications that support timely awareness and reduce anything that does not lead to a useful decision. The goal is not to receive every possible prompt; it is to make important account events harder to miss.
Payment details should also be reviewed before I rely on the app during a busy week. I would verify that the selected payment account and amount are correct, especially after changing banks or using a different payment strategy. A saved routine is helpful only when it remains accurate. This is one of those areas where two extra seconds of checking are more valuable than a fast tap.
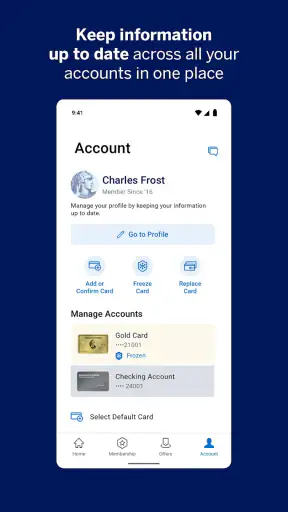
Rewards settings and account information deserve the same treatment. I would keep contact and account details current, then revisit the rewards area when I am ready to redeem rather than assuming the most prominent option is automatically the best one. The app brings the choice close to hand, but the final decision still needs attention to the terms displayed for that account.
A repeatable weekly pattern that saves time
My preferred pattern is a short weekly review: check recent activity, scan for anything unfamiliar, look at the balance, and decide whether a payment is appropriate. This is more reliable than waiting until a due date or only opening the app after receiving a reminder. It spreads the work into a small habit and makes unusual activity easier to recognize.
For someone who travels, I would perform the same review before leaving, during the trip when practical, and after returning. The purpose is not to stare at the account constantly. It is to create clear checkpoints around a period when purchases may be more frequent and unfamiliar. Having the app available makes that routine less dependent on finding a computer.
For rewards users, I would separate earning awareness from redemption decisions. During the weekly review, I might note that rewards are available or that a redemption area is worth checking. I would make the actual redemption later, when I can compare the available choices calmly. This two-step approach reduces the chance of converting rewards simply because I happened to be looking at the account while distracted.
Faster patterns for payments and activity checks
The fastest safe workflow is not necessarily the shortest one. I would open the app, confirm that I am viewing the intended account, glance at recent activity, and only then move to payment or another action. Once that sequence becomes familiar, it takes little time while preserving a useful safety check.
When I need to confirm a purchase, I avoid searching for a broad answer in my memory. I compare the merchant, amount, and timing shown in the account with what I actually bought. That small three-part check is more dependable than recognizing a merchant name alone, since some businesses appear under a billing name that differs from the name on a receipt.
For payments, I prefer a calendar habit over a panic habit. I choose a regular review point that fits my income cycle, then use the app to verify the balance and payment details. If circumstances change, the mobile access makes it easier to respond, but I do not want every payment to be an emergency session. The app is most effective when it supports a plan already understood outside the screen.
There is also a useful division between quick checks and deep checks. A quick check answers, “Has anything changed?” A deep check asks, “Does every item make sense, and is my payment decision right?” I use the app for both, but I do not confuse them. The first can take a moment; the second deserves a slower look, particularly after travel or an unusually active spending period.
Advanced limits and situations where another option wins
The app’s focus is also its main limitation. It is designed around American Express rather than around every financial relationship a person may have. If your daily life involves several card issuers, bank accounts, shared household spending, or detailed category analysis, a broader finance tool may offer a more complete picture. I would keep Amex for account actions while using another service for consolidation, rather than expecting one app to do both jobs equally well.
Users who prefer desktop work may also find the mobile format restrictive for extended review. A phone is excellent for a balance check, a payment, or a quick look at rewards. It is less appealing when I want to compare many transactions side by side or carefully organize financial records. In those cases, the traditional web account or a larger-screen workflow may be more comfortable.
Another limit is that convenience can encourage shallow checking. Seeing a balance is not the same as understanding available spending room, pending activity, or the effect of a payment. I would avoid making a large financial decision from one number on the opening screen. The app gives me access to useful account information, but responsible interpretation still requires context.
Rewards can create a similar trap. Having redemption nearby feels helpful, but the best choice depends on the options shown for the account and what I value. Someone who wants a simple cash-oriented routine may prefer a straightforward redemption approach, while another user may be willing to spend more time comparing possibilities. The app makes the process accessible; it does not remove the trade-off.
I would also skip this app if I do not have an American Express account or if my main objective is general money management. Installing a card-specific app without using that card adds little value. In that situation, a bank app or independent budgeting tool would be a more sensible starting point.
Who should use it and who should keep looking
I think it is a strong fit for an existing American Express customer who wants mobile access to balances, payments, activity, and rewards. It suits people who prefer short, repeatable check-ins and those who want to handle ordinary card tasks while away from a computer. The free price also makes it easy to try as a companion to an existing account rather than a separate financial commitment.
It is less suitable for someone who expects a complete budget planner, a multi-provider dashboard, or an advanced financial analysis workspace. Those users may be happier with a broader app and can treat the Amex app as a specialist tool for actions that need to happen directly on the card account.
The high user response, with around fifteen thousand written reviews alongside its 4.8 average, gives me confidence that the core experience works for many people. I would still judge it by my own workflow rather than by popularity. A well-rated card app cannot compensate for a mismatch between its focused purpose and a user’s need for consolidated finances.
My final view after building a routine around it
Amex is at its best when it becomes a dependable account checkpoint. I would use it to review activity before paying, keep rewards decisions deliberate, and make short weekly checks part of normal card management. Those habits bring more value than simply opening the app whenever a notification appears.
American Express has built a focused finance app that covers the practical actions its cardholders are likely to need. It is free, mature, and supported by a large installed user base, but its specialization matters. I would recommend it to Amex customers who want convenient mobile control and a clear routine. I would not recommend relying on it alone for budgeting across several providers or for detailed long-term financial planning.
My verdict is positive with that boundary in mind. If your financial life already centers on an American Express account, the app can make payments, activity checks, and rewards management feel easier to keep up with. Use the settings thoughtfully, create a repeatable review pattern, and slow down for important decisions. Used that way, it is a useful everyday companion rather than just another icon on the phone.
Pros
- Strong fraud protection and real-time purchase alerts.
- Useful travel benefits for eligible cardholders.
- Detailed spending insights help track expenses.
- Reliable customer support through phone and in-app messaging.
- Wide acceptance in many major retailers and travel services.
Cons
- Some merchants may not accept American Express cards.
- Annual fees can be high on premium cards.
- Rewards often have different value across redemption options.
- Foreign transaction fees may apply to certain cards.
- Approval and benefits depend heavily on credit profile and card type.
FAQs for Amex
What is the Amex app used for?
The Amex app is the mobile companion for American Express cardmembers. After signing in, you can review recent transactions, check your available credit, view statements, make payments, monitor rewards, manage alerts, and access selected account services. The exact tools available may vary depending on your card, country, account status, and the version of the application installed on your device.
Is the Amex app free to download and use?
The Amex app is generally free to download from the official Google Play Store or Apple App Store, and American Express normally does not charge a separate fee simply for using the application. However, your card’s regular fees, interest, foreign transaction charges, or other account costs still apply. Mobile data or roaming charges may also be billed by your network provider.
Can I make payments and manage my Amex card through the app?
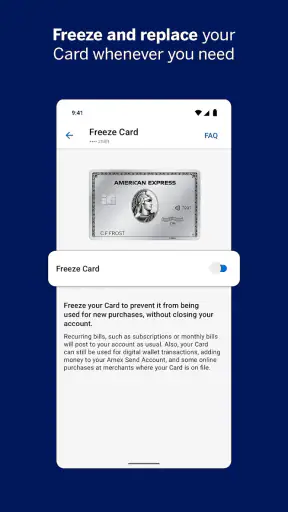
Yes, eligible cardmembers can usually make payments, schedule or review payment activity, inspect due dates, and manage linked bank accounts through the app. You can also freeze or unfreeze a card in supported markets, report certain problems, update alerts, and review account details. Payment features and processing times depend on your country, card product, bank, and account configuration.
Is the Amex app safe for checking my account?
The Amex app is designed with security features such as account authentication, encrypted connections, device verification, and optional biometric sign-in where supported. Even so, users should download it only from an official app store, keep the operating system updated, avoid public or unsecured Wi-Fi for sensitive actions, and never share passwords or one-time verification codes with anyone claiming to represent American Express.
What do I need before downloading and signing in to Amex?
You generally need an eligible American Express account, your online account credentials, and a compatible Android or iOS device with internet access. Some features may require a verified mobile number, email address, or additional security confirmation. Before installing, check that the app is published by the official American Express developer and that your device meets the current operating-system requirements.

Amex
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via android@aexp.com, visit https://www.americanexpress.com/us/customer-service/digital/amex-mobile-app.html, or review their https://www.americanexpress.com/us/content/legal-disclosures/online-privacy-statement.html.










